
BCE, Fed rate cuts: cheap money fuels pyramid effect
Spain's central banks and China cut rates in September. Dominant analysis warns that cheap credit benefits the top while ordinary citizens pay the price.
English · Original discussion in Spanish · Published
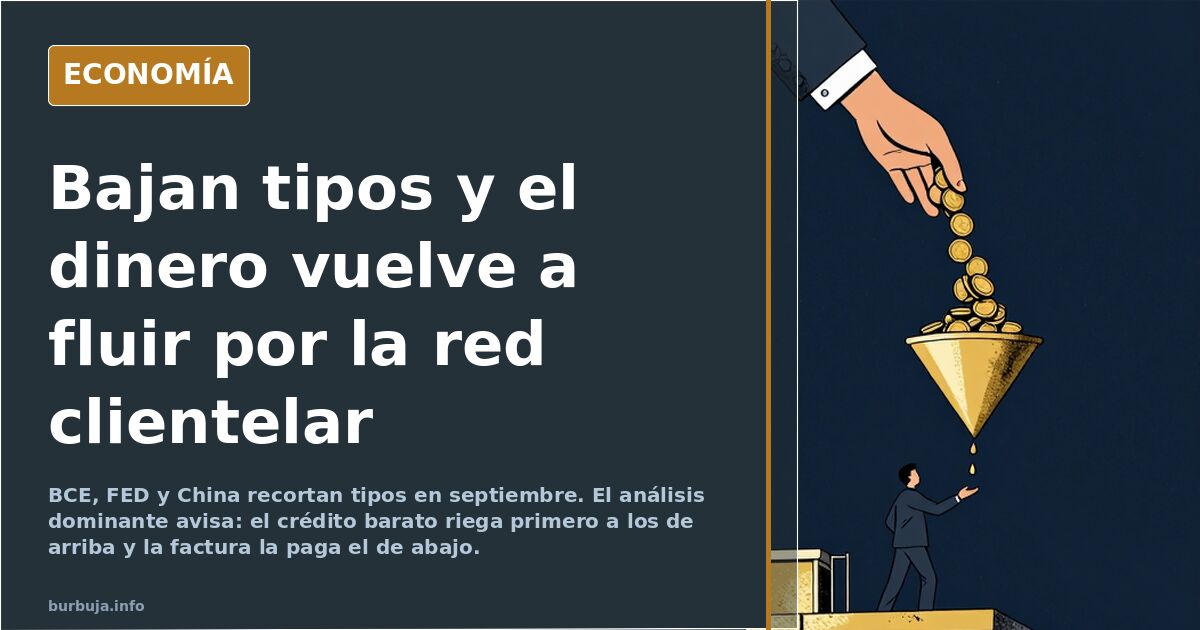
Rate cuts: cheap money flows to the top first
Do you already feel cheaper money in your pocket? The ECB cut by a quarter-point and the Fed by half a point in September, while Bitcoin jumped 5% in a single session. For the dominant analysis in this forum, this move is merely the starting gun for a new round of monetary expansion. The thesis underpinning the discussion is that cheap credit does not reach everyone at once: it flows down through a patronage network where those closest to the money printer benefit first, and those furthest away foot the bill.
What peine with interest rates
The sequence of cuts being discussed is broad: the Bank of Canada lowered rates by 25 basis points to 4.25% on September 4, the ECB cut by 0.25% to 3.50% on September 12, the Fed applied 50 basis points on September 18, and the People's Bank of China touched the 14-day repo rate by 10 basis points on September 23. The Bank of England had already acted on August 1. A coordinated cycle, not an isolated decision.
The immediate discussion was terminological. Some argue that cutting rates is not the same as quantitative easing, while others respond that the effect is identical: credit expansion under another name. The most cited response points out that struggling companies have two options: tap into the free-for-all credit or go bankrupt, and the choice is clear.
Trickle-down economics: who gets paid first
The scheme outlined has three tiers. At the top, investment funds, venture capital, hedge funds, and governments receive money without working, as a reward for trinc specific directives. In the middle, those of us working for these large corporations get paid before prices absorb the expansion, allowing us to buy at old prices. At the bottom, the majority outside this network receives crumbs after prices have already risen. The result, it is argued, is a wealth transfer from bottom to top.
There are nuances here. One analysis suggests that in highly indebted economies, the money printer may not generate inflation if the funds are used to pay existing commitments, such as public salaries and pensions, because spending patterns do not change. Another participant counters that public spending does distort: resources are allocated to goods and services no one demands, making what would otherwise have been produced more expensive.
Is cutting rates the same as printing money?
Not exactly, but the practical effect is similar. Cutting rates does not inject banknotes directly: it lowers the price of money and makes credit cheaper, pushing banks, companies, and consumers to borrow. The banking multiplier does the rest. The discussion gets tangled in whether this constitutes bank money creation, and the technical answer is yes, provided someone comes to borrow, since the liability is already guaranteed by the central bank.
The quote summarizing the critical stance: it’s not printing, it’s quantitative easing; it’s not printing, it’s reverse repo; it’s not printing, they’re partial reserve coefficients. Newspeak, it is said, renames something already known to be harmful.
The tune playing in the labor market
The central prediction of the initial argument is that employment will reactivate. The reasoning: the labor topic was dead since early September, and with cheaper money, job offers will start appearing. Electoral uncertainty in the United States adds noise to the scenario.
Others read the same score backwards. It is pointed out that the rate cut responds to an economic stall on the eve of US elections, not to an expansive impulse. And it is noted that inflation remains uncontrolled: if prices aren’t rising faster, it’s because normal wages can no longer afford them.
Contradictory signals: discounts, gold, and liquidity
There are indications that don’t fit the inflationary narrative. Discounts of 20% on KTM motorcycles, significant sales at Honda, and 50% off at Cortefiel are mentioned, along with accumulated stocks that aren’t selling. Gold, however, is hitting highs in dollars and euros. And the M2 money supply has entered expansion after the deepest contraction since 1960, according to the shared chart.
The most extreme position warns of a real estate burst and a geopolitical scenario stretching the rope. Others expect new stimulus plans, the Draghi plan, and whatever is implemented by whoever wins in the United States, with official inflation at 2.5-3%.
The party continues, credit becomes cheaper, and prices hold. Let each person see which rung of the pyramid they are dancing on.
Also available in: Deutsch
Summary of a discussion on Burbuja.info - Foro de economía, actualidad y política., translated from Spanish and reviewed before publication. Read the full discussion (117 replies).
More summaries
-
Central Banks Cut Rates: Lifeline or Patch?
ECB and Fed cut rates by 0.5% on Oct 8, 2008, in a coordinated move. The euro area borrowing rate failed to react, and the TED spread hit a record.
-
Draghi ends 'whatever it takes': decade of 5% rates
Mario Draghi warns of structural inflation and a decade of ~5% interest rates, cutting household borrowing capacity by up to 45%.
-
China CPI stalls at 0.1% as Europe lags on inflation
China's annual CPI holds at 0.1%, exhausting forecasts, while the highest rate hikes since Volcker fail to return European inflation to the 2% target.
-
Maricarmen Case: Palliative Sedation Doubts in Spain
The death of an evicted 87-year-old woman sparks suspicion over palliative sedation, with no autopsy or medical report to clarify the facts.
-
Forum Debate: Where Are the Drought Predictions?
Users mock drought and sea-level warnings after weeks of rain, while others highlight climate scale and uncertainty.
-
Madrid Govt Denies Ceuta Protest, Then Approves It
Spain's Madrid government office initially banned a pro-Ceuta rally but authorized it hours later, sparking accusations of political bias.